Strategic Investments and Venture Capital Trends
The venture capital environment for mobile gaming remains competitive, particularly for studios that demonstrate an ability to blend casual mechanics with strong monetization. Leading the recent wave of funding is Circle Games, which successfully closed a $25 million Series A round. This investment was led by the global technology conglomerate Tencent, signaling a continued interest from major Chinese firms in diversifying their international portfolios.

The funding round saw significant participation from a syndicate of high-profile investors, including e2vc, Bitkraft Ventures, APY Ventures, and a16z Speedrun. The involvement of a16z’s specialized gaming accelerator, Speedrun, suggests that Circle Games is viewed as a high-growth entity capable of rapid scaling. Data provided by AppMagic highlights the studio’s current momentum; their flagship title, Sort Express, has generated approximately $5.8 million in in-app purchase (IAP) revenue since its launch in early 2025. The success of Sort Express serves as a proof of concept for Circle Games’ development philosophy, which focuses on high-retention puzzle mechanics.
Simultaneously, the real-money gaming (RMG) sector is seeing a shift toward synchronous, skill-based competition. Topdog, a firm specializing in this niche, recently secured $2.5 million in seed funding. While traditional RMG titles often rely on asynchronous play—where players compete against a leaderboard or a recorded score—Topdog is differentiating itself by offering live, turn-by-turn matches. Their portfolio, which includes Basketball Hustle, 21 Hustle, Tilt, and Pinfall, aims to capture the intensity of real-time sports and casino-style competition, catering to a demographic that demands immediate results and direct social engagement.

Regional Market Analysis: The Contraction of Japan
Japan, historically one of the most lucrative mobile gaming markets in the world, is facing a period of cooling. According to a comprehensive report from Sensor Tower, Japan’s mobile game revenue fell by 5.1% year-on-year in 2026, totaling approximately $10 billion (¥1.56 trillion). This decline was mirrored by a 5.4% drop in total downloads, which fell to 585 million.
The downturn in Japan is attributed to several factors, including market saturation and a lack of breakout new intellectual properties that can compete with established "evergreen" titles. Despite the overall contraction, certain genres and titles showed remarkable resilience. Konami’s eFootball reclaimed the top spot on the grossing charts, followed closely by Mixi’s perennial favorite Monster Strike and the globally successful Last War: Survival.

Genre-specific data reveals that 4X strategy games remain the primary revenue driver in the Japanese market, while puzzle games continue to dominate the download charts. Notably, Puzzle Sort saw a 45.8% increase in downloads, suggesting that while Japanese players are spending less on average, their appetite for accessible, high-quality casual content remains robust. The decline in IAP revenue highlights a broader challenge for developers: maintaining monetization depth in an economy where consumer spending is under pressure.
Global Performance and Advertising Benchmarks
August 2026 was a month of significant movement for global revenue leaders. SocialPeta data indicates that Gossip Harbor secured the number one revenue spot on the App Store, highlighting the continued dominance of the merge-narrative subgenre. On Google Play, Roblox maintained its lead, fueled by its massive user-generated content ecosystem and consistent engagement across younger demographics.

One of the most dramatic shifts in the August rankings involved Fate/Grand Order. The title’s 11th-anniversary campaign acted as a massive revenue catalyst, driving IAP earnings up by 548.9% month-on-month. On the App Store alone, the game generated $19.4 million during this period, propelling it back into the global top 20 grossing rankings. This surge underscores the critical importance of "live ops" and anniversary events in extending the lifecycle of gacha-based RPGs.
In terms of user acquisition and downloads, Block Out led the App Store charts, while Roblox remained the most downloaded title on Google Play. Tencent’s Gangstar Mirage City emerged as the fastest riser of the month, climbing to number eight on the global download chart with 11.7 million downloads on Google Play. This performance suggests that Tencent’s internal studios are successfully capturing the demand for open-world action titles on mobile.

The advertising landscape also showed high levels of activity. Vita Mahjong topped both iOS and Android ad charts, indicating a massive push in user acquisition for the puzzle title. Nuverse’s Plants on Fire utilized approximately 7,700 de-duplicated iOS creatives, while Dinosaur-Games’ Last Light deployed a staggering 17,000 Android creatives. These figures represent a growing trend where developers use high-volume creative testing to combat rising CPI (cost-per-install) rates.
The Resurgence of H5 and Browser-Based Gaming
A significant shift in consumer behavior is being documented in the web gaming sector. A collaborative whitepaper from Newzoo and Google reveals that 46% of online consumers aged 13 to 55 now play H5 (HTML5) games on a monthly basis. This figure rises to 60% among the 13-30 age bracket, suggesting that younger players do not distinguish between app-based and browser-based experiences as sharply as previous generations.

The accessibility of H5 games is a primary driver of this growth. Approximately 83% of H5 gamers play on smartphones, and 75% of these users also engage with traditional app-based games. Discovery remains a challenge for the sector; only 23% of players go directly to a gaming portal, while 45% find games through web searches. This reliance on search engines places a premium on SEO and web-based marketing for developers.
The report also found that H5 games provide a significant engagement lift for websites. Platforms that integrate H5 games see visit times increase by roughly 40%. This has prompted major platforms like YouTube to expand their gaming footprint. YouTube has recently continued the rollout of its "Playables" feature across Europe and the Nordics, integrating lightweight web games directly into the video-sharing interface to increase user retention.

Alternative Distribution and the RCS Revolution
As developers seek to bypass the 30% commission fees traditional app stores charge, alternative platforms are gaining traction. Jest, an innovative app store based on RCS (Rich Communication Services) text messaging, has reported a $1 million gross billings run rate within just three months of enabling in-app purchases.
Jest’s model leverages the ubiquity of text messaging to deliver games directly to users without the friction of a traditional app store download. The platform has reported a 15% payer conversion rate among active US users—nearly five times the industry standard for mobile apps. Following 400% usage growth since the second quarter of 2026, Jest is launching a second developer fund. This fund offers up to $1 million across three tiers, with Jest covering messaging fees to allow developers to retain up to 90% of their net revenue. This aggressive fiscal model positions Jest as a serious contender in the diversifying landscape of mobile distribution.

Emerging Hits and Cultural Trends
The "hybridcasual" and niche simulation markets are producing strong individual performers. ABI Games’ Colony Flow, which launched in June, has already surpassed $11 million in lifetime revenue and 7.6 million installs. The game utilizes a "dismantle-the-image" mechanic similar to Pixel Flow but replaces industrial themes with a nature-based ant colony aesthetic. It currently ranks fourth in the top-grossing hybridcasual puzzle charts.
In the hypercasual space, ASMR-themed titles are leveraging social media trends to achieve viral growth. Brocker Bus Studio’s Mystery Dumpling: Unbox ASMR tapped into the TikTok "unboxing" phenomenon, recording 9 million downloads in its launch month. The game has since surpassed 13 million total installs. The "dumpling" theme became so prevalent that AppMagic identified more than ten similar titles released in August alone, highlighting the rapid-fire "fast fashion" nature of hypercasual development.

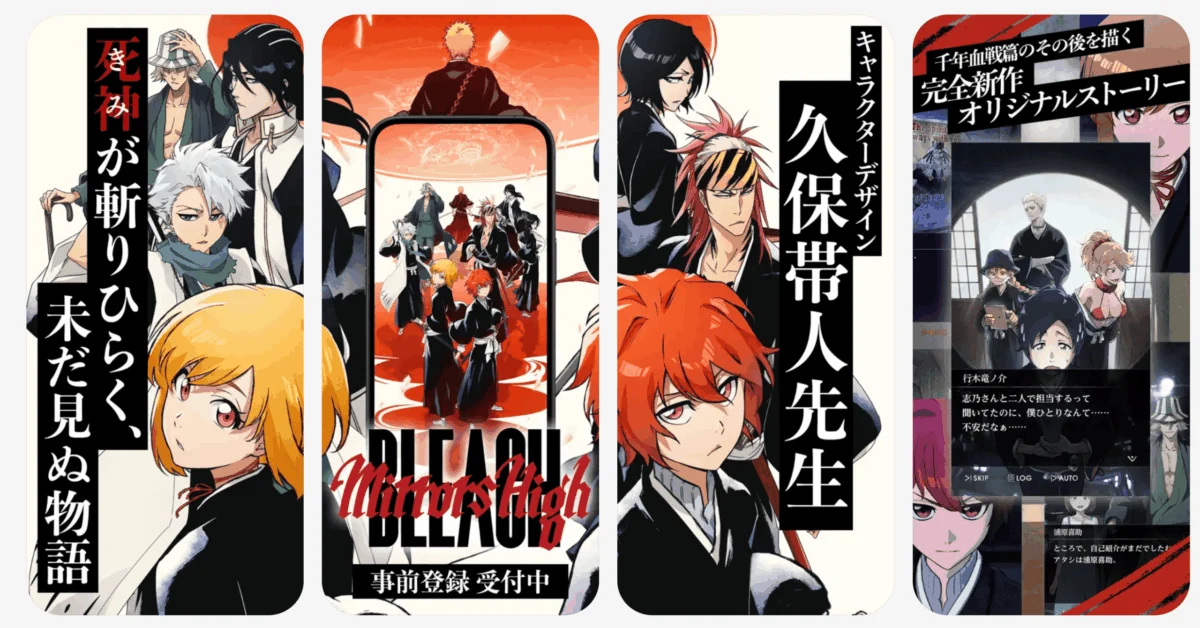
Finally, licensed intellectual properties continue to show strong pre-launch demand. Bandai Namco’s Bleach Mirrors High has surpassed 400,000 pre-registrations within a month of opening. The publisher has incentivized registration by offering iconic characters like Ichigo Kurosaki and Rukia Kuchiki as rewards for reaching the 500,000 milestone. Similarly, My.Games reported that its simulation title Hunting Rivals has hit $3 million in revenue and 1 million monthly active users since its May launch, proving that specialized simulation genres can maintain a dedicated and profitable player base.
Conclusion and Future Outlook
The data from late 2026 paints a picture of a mobile gaming industry that is maturing and diversifying. While traditional markets like Japan are seeing a slight contraction, new avenues for growth are opening in web-based gaming and alternative messaging-based storefronts. The success of high-engagement crossovers, such as the recent 12-day event between Duolingo and Supercell’s Brawl Stars—which saw Duolingo hit 711,000 installs on launch day—demonstrates that non-gaming apps are increasingly using gaming mechanics to drive user acquisition. As the year draws to a close, the ability to innovate in distribution and cross-platform engagement will likely be the deciding factor for market leadership in 2027.
About the Author