The extended reality (XR) industry is currently witnessing a significant pivot from bulky virtual reality (VR) headsets toward sleek, wearable smart glasses. While the consumer appetite for these devices is reaching unprecedented levels, a growing disconnect has emerged between hardware sales and the profitability of the third-party developer ecosystem. Industry data suggests that while hardware manufacturers like Meta and Luxottica are scaling production to meet massive demand, the software landscape remains restricted, leaving independent creators with limited avenues for monetization and sustainable business growth.
The Scaling of Smart Glasses Hardware
The current trajectory of the smart glasses market is defined by aggressive production targets and high consumer adoption rates. Internal memos from the partnership between Meta and Luxottica indicate a strategic push to increase production to between 20 million and 30 million units annually. To put this into perspective, the Meta Quest 2, widely considered the most successful VR headset to date, sold approximately 25 million units over its entire multi-year lifecycle. Achieving similar numbers within a single calendar year for smart glasses signals a fundamental shift in the XR landscape.

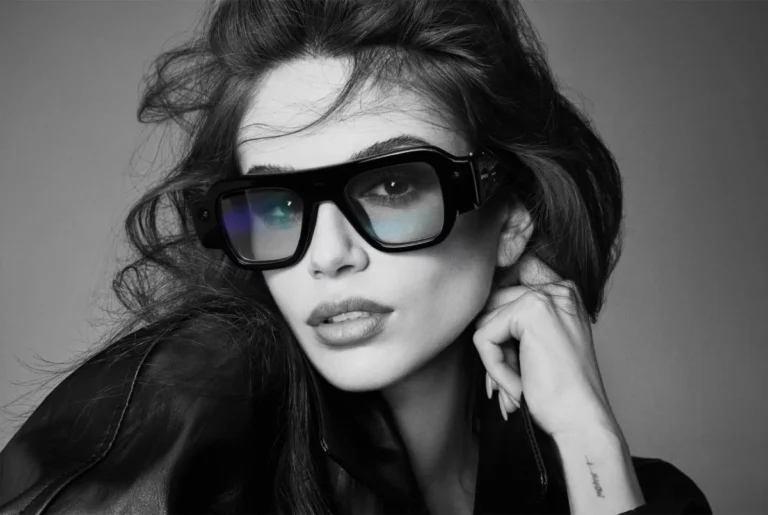
This momentum has triggered a competitive "gold rush" among global technology firms. Samsung is slated to release its own smart glasses in late 2024, while Apple is rumored to be developing a non-Vision Pro wearable for a 2025 or 2026 release. In the Eastern markets, companies such as Huawei, TCL RayNeo, and Alibaba have already deployed various iterations of smart eyewear. Unlike VR, which often requires significant consumer education, smart glasses leverage an existing global habit: the wearing of corrective or protective eyewear. By integrating technology into frames distributed through Luxottica’s vast retail network, manufacturers have bypassed the traditional "tech enthusiast" silo and moved directly into the mainstream fashion and optical markets.
A Chronology of Smart Wearables and Market Evolution
The evolution of smart glasses has been marked by periods of intense hype followed by significant market corrections. Understanding the current "paradox" requires a look at the timeline of the industry:
- 2013–2014: The launch of Google Glass Explorer Edition. Despite high initial interest, the product failed to achieve mainstream success due to its high price point, limited battery life, and significant social backlash regarding privacy and "glassholes."
- 2016–2021: A period of fragmentation. Snap Inc. released several iterations of Spectacles, focusing on social media integration, while enterprise-focused glasses like Google Glass Enterprise Edition and Vuzix found niche applications in logistics.
- 2021–2023: The Meta and Ray-Ban partnership redefined the category. By removing the display in the first generation and focusing on audio and photography, the "Ray-Ban Stories" proved that form factor was more important to consumers than complex AR features.
- 2024–Present: The introduction of multimodal AI. The integration of Meta AI and Google’s Gemini into wearable frames has transformed these devices from simple cameras into proactive assistants, driving the current sales surge.
The Developer Barrier: First-Party Dominance
Despite the millions of units sold, independent developers report significant difficulty in establishing profitable applications. The primary obstacle is the "first-party capture" of the most valuable use cases. When a consumer purchases a pair of smart glasses, the most immediate utilities—photography, video recording, real-time translation, note-taking, and navigation—are already provided by the hardware manufacturer.

For instance, when developers began exploring the possibility of using smart glasses for calorie counting or nutritional analysis via computer vision, Meta integrated a similar feature directly into its OS. Because platform holders like Meta and Google possess nearly infinite resources and data, they can implement "killer apps" at the system level, effectively devaluing third-party attempts to provide similar services. This creates a "Red Ocean" environment where small studios are forced to compete with the very companies that control the distribution platform.
Technical Constraints and SDK Limitations
The current generation of hardware imposes strict limitations on what developers can actually build. The most popular models, such as the Ray-Ban Meta glasses, are primarily audio-first devices. Without a heads-up display (HUD), developers are restricted to voice-based interactions or simple audio cues. While the recent release of the Meta Ray-Ban Display SDK has sparked interest by offering a monocular display for short-form information, it is not yet robust enough for complex applications.
Furthermore, Software Development Kits (SDKs) remain in their infancy. Current restrictions often prevent third-party apps from accessing the camera feed in real-time due to privacy concerns and battery management protocols. In many cases, "apps" for smart glasses are not native to the hardware but are instead "companion apps" running on a tethered smartphone. This dilution makes it difficult for users to discover new tools, as they are buried within the millions of entries in the iOS App Store or Google Play Store, rather than being showcased in a dedicated smart glasses marketplace.

The Fragmentation of Ecosystems
The lack of industry-wide standards further complicates the path to profitability. In the VR space, the adoption of OpenXR allowed developers to port games across Oculus, SteamVR, and Pico with relative ease. The smart glasses market, however, remains siloed. An application developed for Meta’s ecosystem cannot easily transition to Samsung’s upcoming glasses or Huawei’s existing hardware.
While projects like Mentra OS aim to create an open-source operating system for all smart glasses, and Google’s Android XR seeks to unify the hardware landscape, the current environment is a "Far West" of proprietary code. For a small developer, the cost of maintaining separate builds for five different hardware platforms often outweighs the potential revenue from a limited user base on each.
Strategic Shifts: The Enterprise and B2B Opportunity
Given the hurdles in the consumer market, market analysts suggest that the immediate "money" in smart glasses lies in the enterprise and B2B sectors. Unlike general consumers, industrial and corporate clients have specific, high-value problems that first-party AI assistants may not address.

- On-Premises AI and Security: Many corporations are hesitant to feed sensitive proprietary data into public AI models like Gemini or Meta AI. This creates an opening for developers to build secure, on-premises AI assistants that run on specialized hardware like Vive Eagle or Mentra-based systems.
- Specialized Training and Logistics: Following the trajectory of the original Google Glass, smart glasses are finding renewed utility in warehouse management, where hands-free barcode scanning and "pick-and-pack" instructions provide measurable ROI.
- Accessibility and Research: Developers are finding success in niche markets, such as creating real-time captioning for the hearing impaired or visual aid overlays for those with low vision. These applications, while serving a smaller demographic, often command higher price points and foster greater user loyalty.
Broader Implications and Future Outlook
The long-term success of the smart glasses ecosystem depends on the transition from "smart wearables" to "true AR glasses." Current devices are largely viewed as cameras with speakers; the "true" breakthrough will occur when transparent, high-field-of-view optics allow for digital objects to be anchored in the physical world.
However, even with technological advancements, the industry must navigate the "social acceptance" hurdle. Recent reports of "pervert glasses" stigmas and the banning of smart eyewear in certain public venues suggest that privacy remains a volatile issue. If the public perception of these devices sours, the "20-30 million unit" projections may face a sharp downward revision, similar to the decline of early wearables in the mid-2010s.
For the independent developer, the current phase is one of experimentation and "wait-and-see." While the hardware is selling, the infrastructure for a thriving third-party economy—including dedicated app stores, unified SDKs, and open camera access—is still under construction. Industry observers suggest that the smart glasses market may follow the path of the smartwatch: a device that took several years to find its "killer" utility in health and fitness before becoming a staple of the developer economy. Until that maturation occurs, the profitability of smart glasses will likely remain concentrated in the hands of the hardware giants.
About the Author